

- Article
- Comments (0)
Time to get over inflation
Reserve Bank of India is still following a 'control inflation' strategy, at least the recent monetary policy announcements suggest so. But with the country's GDP growth slowing down to 5.8 per cent, it soon needs to change its focus. By ashish kumar
Tags : crr | reserve bank of india | GDP growth | inflation | |
 Once again the Reserve Bank of India has left key policy rates unchanged and decided to deal with the situation with a 25 basis point cut in cash reserve ratio (CRR), the portion of deposits banks are mandated to keep with the RBI. This move, which means banks will now have to keep lesser deposit with the apex bank, intends to release as much as Rs175 billion into the banking system and showcases RBI's change in focus from controlling inflation to supporting growth, more so for this is the second time RBI has resorted to a CRR cut within a time span of one and half months. But the question remains, when the country's growth rate is dipping faster than expected, what good this wait and watch policy from RBI is going to do?
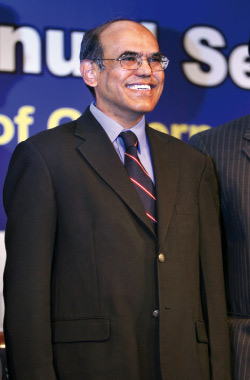
During the quarter ended June 2012, India's GDP growth slumped to 5.5 per cent as compared to an eight per cent growth registered during the same period last year. At the same time, both wholesale and retail inflation remained stubbornly high. So far, RBI has been trying to control inflation single-mindedly. However, after a dozen rate hikes in the past three years, though it managed to bring inflation down from nearly double digits to a seven to eight per cent level, it is still exorbitantly high as far as the economy's comfort is concerned and remains the core challenge. As per Dinesh Thakkar, Chairman and Managing Director, Angel Broking, “I believe that high food prices, the pass through effect of fuel price hikes and sticky core inflation are likely to keep inflation elevated until December.” Even the governor of the apex bank D Subbarao admits RBI's failure in controlling inflation, saying: “I must admit that, even at a personal level, I do not know how to interpret inflation." Still, by not changing key policy rates, RBI has reiterated that managing inflation is its top priority, more so after the inflation trajectory is revised upward to 7.5 per cent in this policy review from the seven per cent expected earlier.
On the other hand, though RBI has been neglecting the growth aspects of the country while taking policy decisions, it will now face tremendous pressure from the government to take it more seriously; at least for the fact that the country's growth expectations are now revised to 5.8 per cent for the fiscal from 6.5 per cent estimated in July.
Under such circumstances, this CRR cut looks more like an action taken to meet the currency demand and address the liquidity crunch that may occur during the festive season. Reacting to the monetary policy announcements, Sandeep Nanda, Chief Investment Officer, Bharti AXA Life Insurance said, "The decision to keep policy rates unchanged seems to have disappointed markets given the recent government actions. The CRR cut was more to preempt liquidity tightness due to the festival related currency demand."
Even if the move intends to ease liquidity pressure, this alone may not serve the purpose for the GDP. Industrial production is set to face a serious situation soon for the fact that India Inc's capex plans have been on hold for quite sometime now. And unless and until they see funds coming their way, they are not going to get going with their plans. But for funds to come at a time when the country's primary market is providing no dough and interest rates are too high for borrower's comfort, RBI has to come forward with some decisive solutions. It has to cut down the key policy rates bringing down borrowing rates. A similar move at this point of time, when the government has already increased India Inc's woes by increasing fuel prices, would have helped the market sentiment to revive to some extent. As Nirmal Jain, Chairman, IIFL points out, "While inflation is an issue, a repo rate cut at this stage would have been similar magic (what reform announcements did to stock market) to turnaround the sentiment radically, for investment in new projects, expansion and also for capital flow from foreign investors. It could have done little incremental damage to inflation or inflationary expectations."
As said earlier it is time for RBI to be decisive and understanding about the condition of the economy, if one has to choose between two evils of inflation and low growth, the former is the lesser one. Paradoxically, we need growth to address inflation in the long term. "A growing economy like ours, needs a conducive environment for investment and capital formation, to ease supply constraint," adds Jain. However, he also clarifies that the CRR cut will help liquidity and pressure on lending rate. It will also nullify the negative impact on increased provisioning on restructured assets. But it is not enough to provide the desired boost to the economy.
Having said that, one must also consider the fact that RBI alone cannot deal with the situation. So far, it has somehow managed to keep inflation under 10 per cent, but with supply-side constraints continuing to trouble the nation and the government bowing down to fiscal deficit, controlling inflation through monetary policy measures may not be possible for long. Thus the government also needs to intervene with radical steps like reforms and other measures to remove supply-side bottlenecks to help RBI in controlling inflation. So that the apex bank can change its focus towards policies to help the country's growth rate to come back on track.
ashish.kumar@planmanmedia.com


 Issue Dated: Feb 5, 2017