

- Article
- Comments (0)
The slow GDP burn
Economists across the board are astounded at the failure of the government to sustain high GDP growth rates. KS Narayanan and shiv sunny analyse the consequences of this failure.
Tags : GDP | BRIC | economic growth |
 When India clocked 5.5 per cent GDP growth in 2001, it began to script a new chapter in its economic landscape. Global players could no longer choose to ignore it or have a condescending attitude towards its people or economy. So much so that India was bracketed along with other emerging economies and it became sought after. In the same year Jim' O Neil, Chairman of Goldman Sachs Asset Management, coined the term BRIC, an acronym that stands for Brazil, Russia, India, and China. India was one of the four rapidly developing countries that came to symbolize the shift in global economic power away from the developed G7 economies.
The following year, GDP growth tumbled to 4 per cent briefly. But both India and its GDP growth bounced back to 8.1 in 2003 and maintained it above 9 per cent till 2007. As winds of global financial crisis blew, India's growth story began to plummet to 6.7 GDP growth first and regained to 8.4 per cent for two consecutive years. Plagued by policy parlaysis, last year India's GDP growth hit a new low at 6.9 per cent. For the current financial year several global analysts and institutions have projected below 6 per cent growth for India.
The GDP growth rate for the second quarter of this fiscal (July- September 2012) is pegged at 5.3 percent as per the latest growth figures recently released by the Central Statistics Office (CSO). The fact that this is the third consecutive quarter in which the GDP growth rate has hovered around this rate forces one to conclude that the budget forecast of a 7.6 per cent growth rate remains an elusive dream.
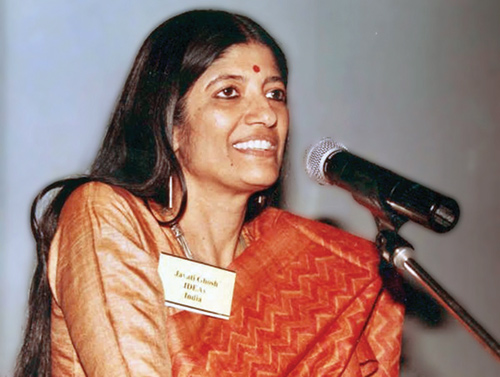
Prof. Jayati Ghosh at the Centre for Economic Studies and Planning, School of Social Sciences at the prestigious Jawaharlal Nehru University wonders why growth revolves around the GDP. "We have an obsession with just the GDP growth rate without looking at the quality of that growth, without bothering whether it serves the requirements of the people. The development projects in India are far from complete. The inequalities are huge. There is just no development in the bottom 50 per cent of the population. This clearly gives a true practical idea of the shamble the Indian economy is in. We have been in a bad shape since long already. And a lot of our recent GDP growth has been because of those services which are basically trickling out of our country and going into multinational corporations or in pockets of large companies which come from the unfair possession of our resources.
I would not celebrate 10 per cent GDP growth as being
wonderful".
Prof. Ghosh, a leading left leaning economist, wonders whether the Indian government has a plan 'B'. "Government does not say that well okay, if not GDP growth, let us then look at employment, let us look at what we can do to make sure that the slowdown does not cause job loss, look at what to do to improve the condition of the general people. That is what is my concern".
How can they have plan 'B' when the UPA II is tarnished by shoddy deals, the highest level of corruption independent India has ever seen, uncontrolled price rise, high unemployment and day to day squabbling amidst allies. "What is more shocking is the hopelessness of this government to control this uncontrolled mess," remarks Dr Suvrokamal Dutta, another well economist and public intellectual.
Further describing Prime Minister Dr Manmohan Singh as a brilliant econmist par excellence, Dutta wonders why he hasn’t been able to control inflation and corruption – a question that is being asked by every common Indian today. “With highest regards for our honorable Prime Minister, I still cannot understand what is stopping him from taking hard and punitive action. As an economist I understand this simple fact that price rise can be controlled by taking simple measures on the demand and supply side and by directing the state governments to support the center in its measures and by taking the hoarders and black marketers head on," he says.
The dominant opinion among economists attribute the government’s inaction and policy paralysis for the current predicament. If the state of affair continues unabated, situation would not only worsen but have a tragic end. "There has been notable inertia on the policy front and continued failure to address fiscal imbalance. Moreover, the high fiscal deficit built up by the government has crowded out the private sector. As a result, an amalgam of low growth and high inflation can weaken the economy further. Eventually slower growth can lead to unemployment, sluggish tax collections, stressed government budgets and flight of capital," warns Prof. P M Mathew of Bangalore based Christ University.
No wonder several economists have called for focus on reforms and governance aimed at revival of growth. What is required is a holistic approach and not mere macroeconomic policy management influenced and conditioned by the political environment. This needs structural reforms both at the central as well as the state levels. To that extent, fiscal deficit must remain at the budgetary level. However, the million dollar question is whether our political class is paying heed to these calls?
Prof Ghosh questions whether the government will ever deliver on its promises. “I am angry with the government that they are not serious about their own commitments. The government had promised us universal education, food security bill and a number of other things. But it does not show any seriousness about the delivery of these things."
Anybody listening?


 Issue Dated: Feb 5, 2017